In our community, buying a home is often a family project: parents contribute savings, adult children carry the loan, maybe a sibling moves into the back bedroom. I have helped many families do exactly this in San Jose. Done right, it is a powerful way into the market. Done casually, it causes real problems years later. Here is how to do it right.
1. Decide who is on the loan and who is on title
These are two different things. On the loan means your income and credit qualify and you are responsible for payments. On title means you legally own a share. A parent can be on title without being on the loan, or help with the down payment as a gift and be on neither. Talk through this before you talk to a lender.
2. Pick the right way to hold title
- Joint tenancy: equal shares, right of survivorship (when one owner passes, their share goes to the others automatically).
- Tenants in common: unequal shares allowed (60/40, for example), each share can be passed to heirs.
- Living trust: frequently the best choice for families; avoids probate and spells out what happens later.
A real estate attorney or estate planner should make this call with you — I will connect you with one, and the cost is small compared to the home.
3. Write the family agreement down
Who pays the mortgage, taxes and repairs? What happens if one person wants to sell or move out? How is a future sale split if contributions were unequal? One page, signed by everyone, prevents most of the disagreements I have seen.
4. Choose the house for the way you will actually live
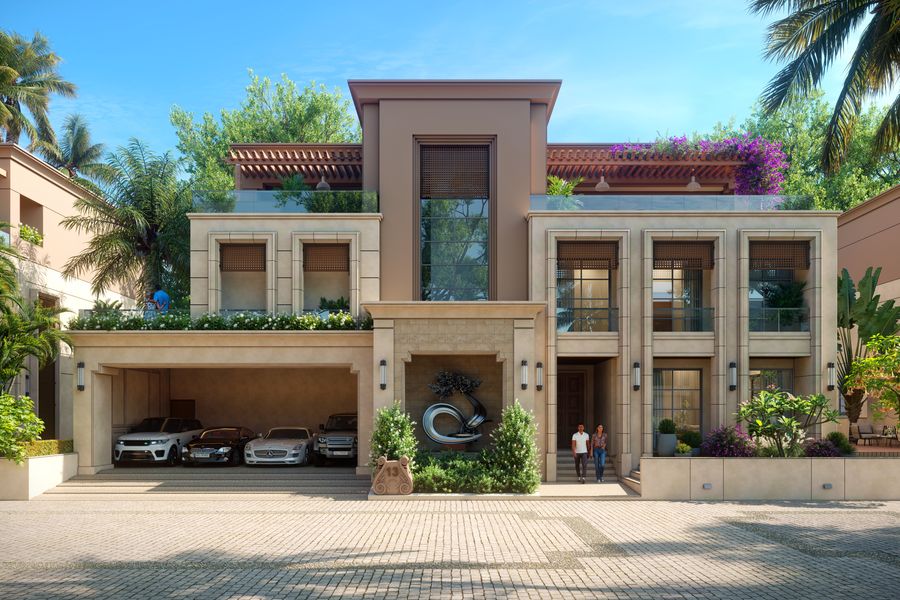
Multigenerational households do best with: a bedroom and full bath on the ground floor for parents, a separate entrance or an ADU, two living areas, and parking for three or more cars. Neighborhoods where I see this work well: Evergreen, Berryessa, Blossom Valley, parts of Milpitas and Fremont.
5. Know the loan options
Lenders allow non-occupant co-borrowers on many conventional and FHA loans, and gift funds from family are accepted with a gift letter. Some programs also count expected rental income from a permitted ADU. A good lender will model two or three structures for you.
If your family is thinking about buying together, let's sit down — in Vietnamese or English, with everyone at the table. Schedule a conversation.
Tóm tắt tiếng Việt
Nhiều gia đình Việt mua nhà chung cả nhà: cha mẹ góp tiền, con đứng loan. Làm đúng thì rất hay, làm qua loa thì vài năm sau dễ rắc rối.
- Ai đứng loan, ai đứng tên (title) là hai chuyện khác nhau — bàn trước.
- Cách đứng tên: joint tenancy (chia đều), tenants in common (chia theo tỷ lệ), hoặc living trust (thường tốt nhất cho gia đình). Nên hỏi luật sư.
- Viết thỏa thuận gia đình một trang: ai trả gì, nếu một người muốn bán thì sao, chia tiền ra sao.
- Chọn nhà có phòng ngủ + phòng tắm tầng trệt cho cha mẹ, lối đi riêng hoặc ADU, đậu được 3 xe.
- Loan cho phép người đồng vay không ở và tiền gia đình cho (gift letter).
Ken ngồi xuống với cả nhà, nói tiếng Việt. Hẹn Ken.